What Is a Home Appraisal and How Does It Work in Northern California?
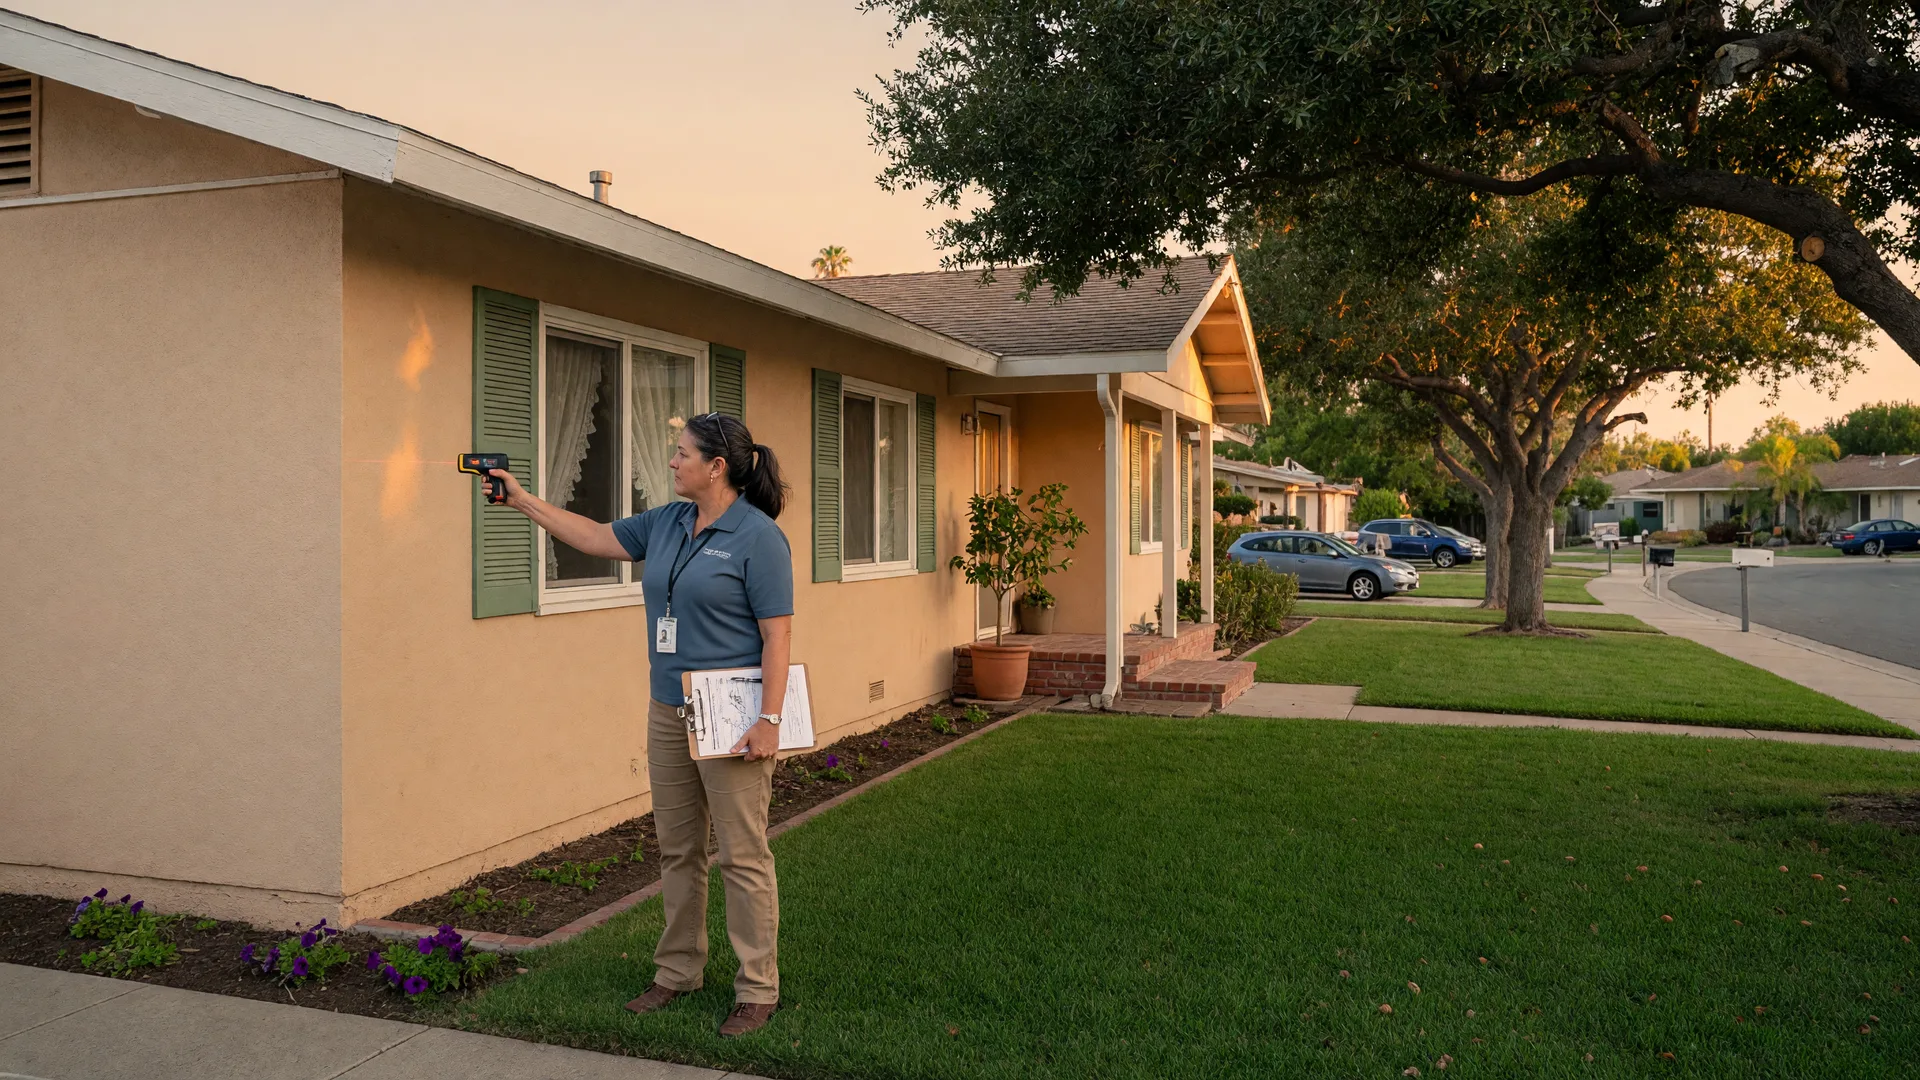
A home appraisal is an independent estimate of a property's market value, prepared by a licensed appraiser. When you're buying with a mortgage, your lender orders an appraisal to make sure the home is worth the amount you're borrowing. It's a normal, expected step in the process, and it protects both you and the lender. Here's what an appraisal involves in Northern California and why it matters for your purchase.
Why Lenders Require an Appraisal
Your lender wants to know that the home offers enough security for the loan. If you were to stop making payments, the lender needs to be able to recover the balance by selling the property. So the appraisal confirms that your purchase price is reasonable compared with what similar homes have sold for recently. It's not about judging whether you got a good deal, it's about verifying value.
What an Appraiser Looks At
Appraisers consider three main things: the condition and features of the home, recent sales of comparable properties, and the local market. During the visit, they measure the home, note the number of bedrooms and bathrooms, and assess the overall condition, upgrades, lot size, and any special features. In the Sacramento Valley, factors like a newer roof, updated kitchen, or a well-maintained yard can all play a role.
How the Value Is Determined
The appraiser compares your home to recently sold homes that are similar in size, age, and location, often called comps. They adjust for differences, such as a larger lot in Plumas Lake or a remodeled kitchen in Lincoln, to arrive at a fair market value. The result is a detailed report your lender reviews before approving the loan.
What Happens If the Appraisal Comes in Low?
If the appraised value is lower than your offer price, your lender will only finance based on the appraised amount, which can create a gap. You have options: negotiate a lower price with the seller, pay the difference in cash, request a reconsideration of value with supporting comps, or, in rare cases, walk away during your appraisal contingency. This is exactly the kind of moment where an experienced agent earns their keep, because we can gather evidence and negotiate on your behalf.
Appraisal vs. Inspection: They're Different
People often confuse the appraisal with the home inspection, but they serve different purposes. The appraisal is about value for your lender, while the inspection is about condition for you. A home can appraise at full value and still have issues an inspection uncovers, so it's important to do both. If you're wondering how they fit into the overall timeline, my guide to escrow and closing walks through it step by step.
Tips for a Smooth Appraisal
For sellers, a clean, well-maintained home and easy access for the appraiser help things go smoothly. For buyers, the main job is simply to be patient while it happens. Appraisals typically take a couple of weeks and are scheduled by your lender, so you don't need to arrange it yourself. If you're buying a newer home in Wheatland or a single-story in Yuba City, the process is much the same.
The Bottom Line
An appraisal is a routine safeguard that keeps your purchase grounded in real market value. Understanding it ahead of time takes away a lot of the worry, because you'll know what's happening and why.
If you're ready to buy in Northern California and want a guide who will keep you informed through the appraisal and beyond, reach out or schedule a free consultation. Let's talk about your goals and the communities that could be the right fit.